Insurance Choices for Mixed Breeds — Mixed-Breed Dog Special 2026
Mixed-breed dogs do not have a fixed breed profile, yet applications often ask which breed they resemble. The bigger hea
Insurance Choices for Mixed-Breed Dogs — 2026 Special Feature
Mixed-breed dogs do not have a fixed breed profile, yet applications often ask which breed they resemble. The bigger headache is that you can complete the purchase with your credit card and only later discover that outpatient care, surgery, or chronic disease is not covered. The Paw Editor has compiled the most important underwriting, waiting-period, and claims questions for 2026 into a checklist you can take straight to an agent.
Why Buy Insurance for Your Pet?
Pet medical care is not covered by Taiwan’s National Health Insurance (NHI). A single emergency visit, hospitalization, or surgery can leave owners facing expenses in the thousands. Follow-up testing, medication, anesthesia, and pathology analysis may add further costs. Pets cannot tell us where they are uncomfortable, so owners must rely on symptoms to decide when to seek veterinary care—and sometimes have to make sudden decisions about emergencies or major surgery.
The value of insurance is not to eliminate medical expenses, but to spread some risks that are infrequent yet potentially financially devastating. How much you can actually recover depends on the coverage, waiting periods, deductibles, and annual limits.
When it comes to mixed-breed dogs, the premium should not be the only consideration. Although they do not have a fixed breed profile, they may still have breed-related risks such as brachycephalic, or short-nosed, traits, curled tails, joint or orthopedic problems, or specific hereditary diseases. Age, weight, prior medical history, and living environment can also affect underwriting outcomes.
Before applying, it is worth estimating three things:
- Whether the monthly premium fits within a sustainable budget
- Whether your current savings could cover surgery if your dog needs it
- Whether the policy’s annual limit is high enough to transfer the major financial risk
If all three are out of reach, there is no need to buy a product that does not meet your needs simply to say you have insurance. Clarifying your risks before deciding whether to purchase coverage is more important than chasing the lowest premium.
Key Considerations and Common Pitfalls
Coverage and Exclusions
The fact that a policy is called “pet medical insurance” does not mean every medical expense is covered. At a minimum, confirm the following:
-
Whether accidents and illness are covered separately
Some products cover accidents only, meaning a common cold, dermatitis, or chronic condition may not be included. Also confirm whether illness coverage includes outpatient visits, hospitalization, surgery, medication, diagnostic testing, and imaging. -
Which expenses are eligible for reimbursement
Preoperative testing, pathology, hospital charges, prescription medication, anesthesia, and post-discharge follow-ups may fall under different coverage categories. -
What is permanently excluded
Symptoms that existed before the policy was purchased, congenital conditions, hereditary diseases, dental treatment, breeding-related veterinary care, weight-loss or cosmetic services, and treatments not recommended by a veterinarian may all be excluded. -
Whether a referral or prior authorization is required
Some policies require a referral from a veterinary hospital or prior authorization from the insurer before hospitalization or surgery. Failing to follow the required process may affect a claim. -
How medical necessity is determined
A veterinarian’s recommendation does not necessarily mean the policy must pay. Whether a service would have been covered under Taiwan’s NHI, whether medication is necessary, and whether the selected tests are reasonable may all become review factors.
In addition to medical coverage, distinguish third-party liability, lost-pet coverage, burial expenses, legal liability, and other optional benefits. Third-party liability insurance covers risks such as your pet injuring someone or damaging property; it does not replace medical insurance.
Waiting-Period Length
Waiting periods are one of the thresholds most easily overlooked when purchasing coverage. Accidents and illness may have different waiting periods, while chronic conditions, specified surgeries, or recurrent diseases may have separate periods. Common waiting periods can range from a few dozen days to several months, but definitions vary by insurer, so one company’s timeline cannot be used to estimate another’s.
Be sure to confirm the following in writing:
- Whether the waiting period begins on the policy’s effective date, payment date, or underwriting date
- Whether t separate schedule for accidents, illness, and specified conditions
- How medical treatment, diagnostic testing, and hospitalization during the waiting period are treated
- Whether pre-existing conditions remain excluded after the waiting period ends
- Whether the waiting period resets upon renewal
A shorter waiting period is not necessarily better. A product may have a short waiting period while excluding chronic conditions, anesthesia, or pre-existing symptoms, resulting in more limited coverage in practice.
Annual Limits and Deductibles
The “maximum annual benefit” is the highest amount the policy will reimburse during the year; it does not mean every expense will be reimbursed up to the same amount. Common limit structures include per-incident limits, per-condition limits, annual aggregate limits, and lifetime limits.
Deductibles may operate as follows:
- Per-incident deductible: Deducted once for each qualifying incident
- Per-treatment deductible: Calculated separately for outpatient care, hospitalization, or surgery
- Annual deductible: Deducted only once across the entire year
- Coinsurance: After the deductible is applied, the owner pays the percentage specified in the policy
You can use the following framework to evaluate a policy:
Insurer payout = policy-covered, medically necessary expenses − deductible − the owner’s coinsurance share and other nonpayable items, subject to the applicable annual or per-incident limit.
For example, a policy may have a high annual limit but also a high deductible and a low per-treatment limit, leaving its practical reimbursement capacity fairly limited. When comparing options, evaluate the annual limit, deductible, coinsurance, and per-incident limit together rather than looking at any one figure in isolation.
Common Mistakes When Insuring a Mixed-Breed Dog
Incorrect breed information is a common risk. If the application asks you to describe a mixed-breed dog’s appearance or estimated breed percentages, do not decide on your own that the dog is “exactly” a particular breed. Use information provided by the veterinary hospital, microchip records, or pedigree documentation. Inconsistencies may become a source of dispute when a claim is reviewed.
You should also pay attention to the following:
- Whether symptoms that appeared before enrollment are classified as pre-existing
- Whether an agent’s verbal assurance that something “is covered” is reflected in the policy wording
- Whether coverage purchased through an online platform is identical to the insurer’s coverage
- Whether advancing age at renewal changes the premium or scope of coverage
- Whether the policy renews automatically, and what happens if you choose not to renew
Four Insurance Plans Compared Side by Side
Companies may adjust their product combinations during 2026, and the Paw Editor will not force insurers whose terms have not been verified into a ranking. Instead, the four common plan types below are put through the same “stress test.” Once you have formal quotes, you can replace Plans A, B, C, and D with the actual insurers.
| Plan | Coverage | Cost | Claims Speed | Customer Support |
|---|---|---|---|---|
| Plan A: Basic accident-only | Primarily covers outpatient care, hospitalization, surgery, and medication arising from accidents; illness is generally outside the main scope | Generally falls within the lower-price tier, but a formal quote based on the dog’s information is still required | Usually easier to assess when the case is straightforward; claims are still subject to review | Confirm online claim submission, case tracking, and how missing documents can be supplied |
| Plan B: Combined accident and illness | Covers both accidents and common illnesses, usually with broader coverage, but excludes pre-existing conditions and specified diseases | Usually mid- to high-priced; annual limits and coinsurance are the key considerations | Diagnoses, waiting periods, pre-existing conditions, and medical necessity must be reviewed, so more complete documentation should be prepared before submission | Check whether customer support staff understand disease-related policy terms rather than handling only straightforward accidents |
| Plan C: High annual limit | Offers coverage similar to a comprehensive plan but with higher annual or per-incident reimbursement limits | Usually more expensive; whether it offers value depends on the deductible and actual needs | Large claims may require additional documents or cross-team review; advertised processing speed should not be trusted on its own | Ask about claim-status notifications, dedicated case follow-up, and assistance for urgent cases |
| Plan D: Comprehensive coverage with add-ons | May add third-party liability, lost-pet, burial, or dental coverage alongside medical protection | Total cost varies according to the selected add-ons; the base premium alone is not enough | Different benefits may be handled as separate claims; confirm whether they can be submitted together or separately | Check whether a single point of contact coordinates everything to avoid repeated transfers between coverage areas |
The table’s real purpose is not to identify the “fastest” or “cheapest” option immediately, but to place all four insurers within the same comparison framework. At a minimum, complete the following four steps when evaluating them:
Compare Using the Same Policy Terms
Ask all four insurers to quote the same mixed-breed dog at the same age and weight, using the same annual limit and deductible. If Insurer A offers a higher benefit limit while Insurer B has a lower deductible, you cannot compare their total premiums directly.
Test Four Scenarios
Give the following situations to an agent and ask whether each would be paid in full, paid in part, or excluded, with the relevant policy provisions identified:
- An outpatient examination, blood tests, and prescription medication
- Hospitalization and surgery after the waiting period
- Long-term follow-up visits and testing for a chronic condition
- A dog accidentally injuring a third party or damaging property
Ask About the Real Claims-Processing Speed
Rather than asking only, “How long will it take to receive payment?” ask:
- What channels are available for submitting a claim?
- What additional documents will be required after the initial claim notification?
- Is a claim number and status-tracking service provided?
- What situations qualify for installment payments or urgent assistance?
- Can the veterinary hospital submit the claim directly, or must the owner pay first?
Compare Customer Support, Not Just Sales Agents
An agent’s familiarity with a product does not mean the insurer’s customer support team is equally familiar with it. Call the customer service center and ask about a specific scenario involving pre-existing conditions, waiting periods, and coinsurance, then compare how clear and consistent the answers are.
Paw Editor’s Reminders / FAQ
Q1: What should owners watch for with brachycephalic dogs?
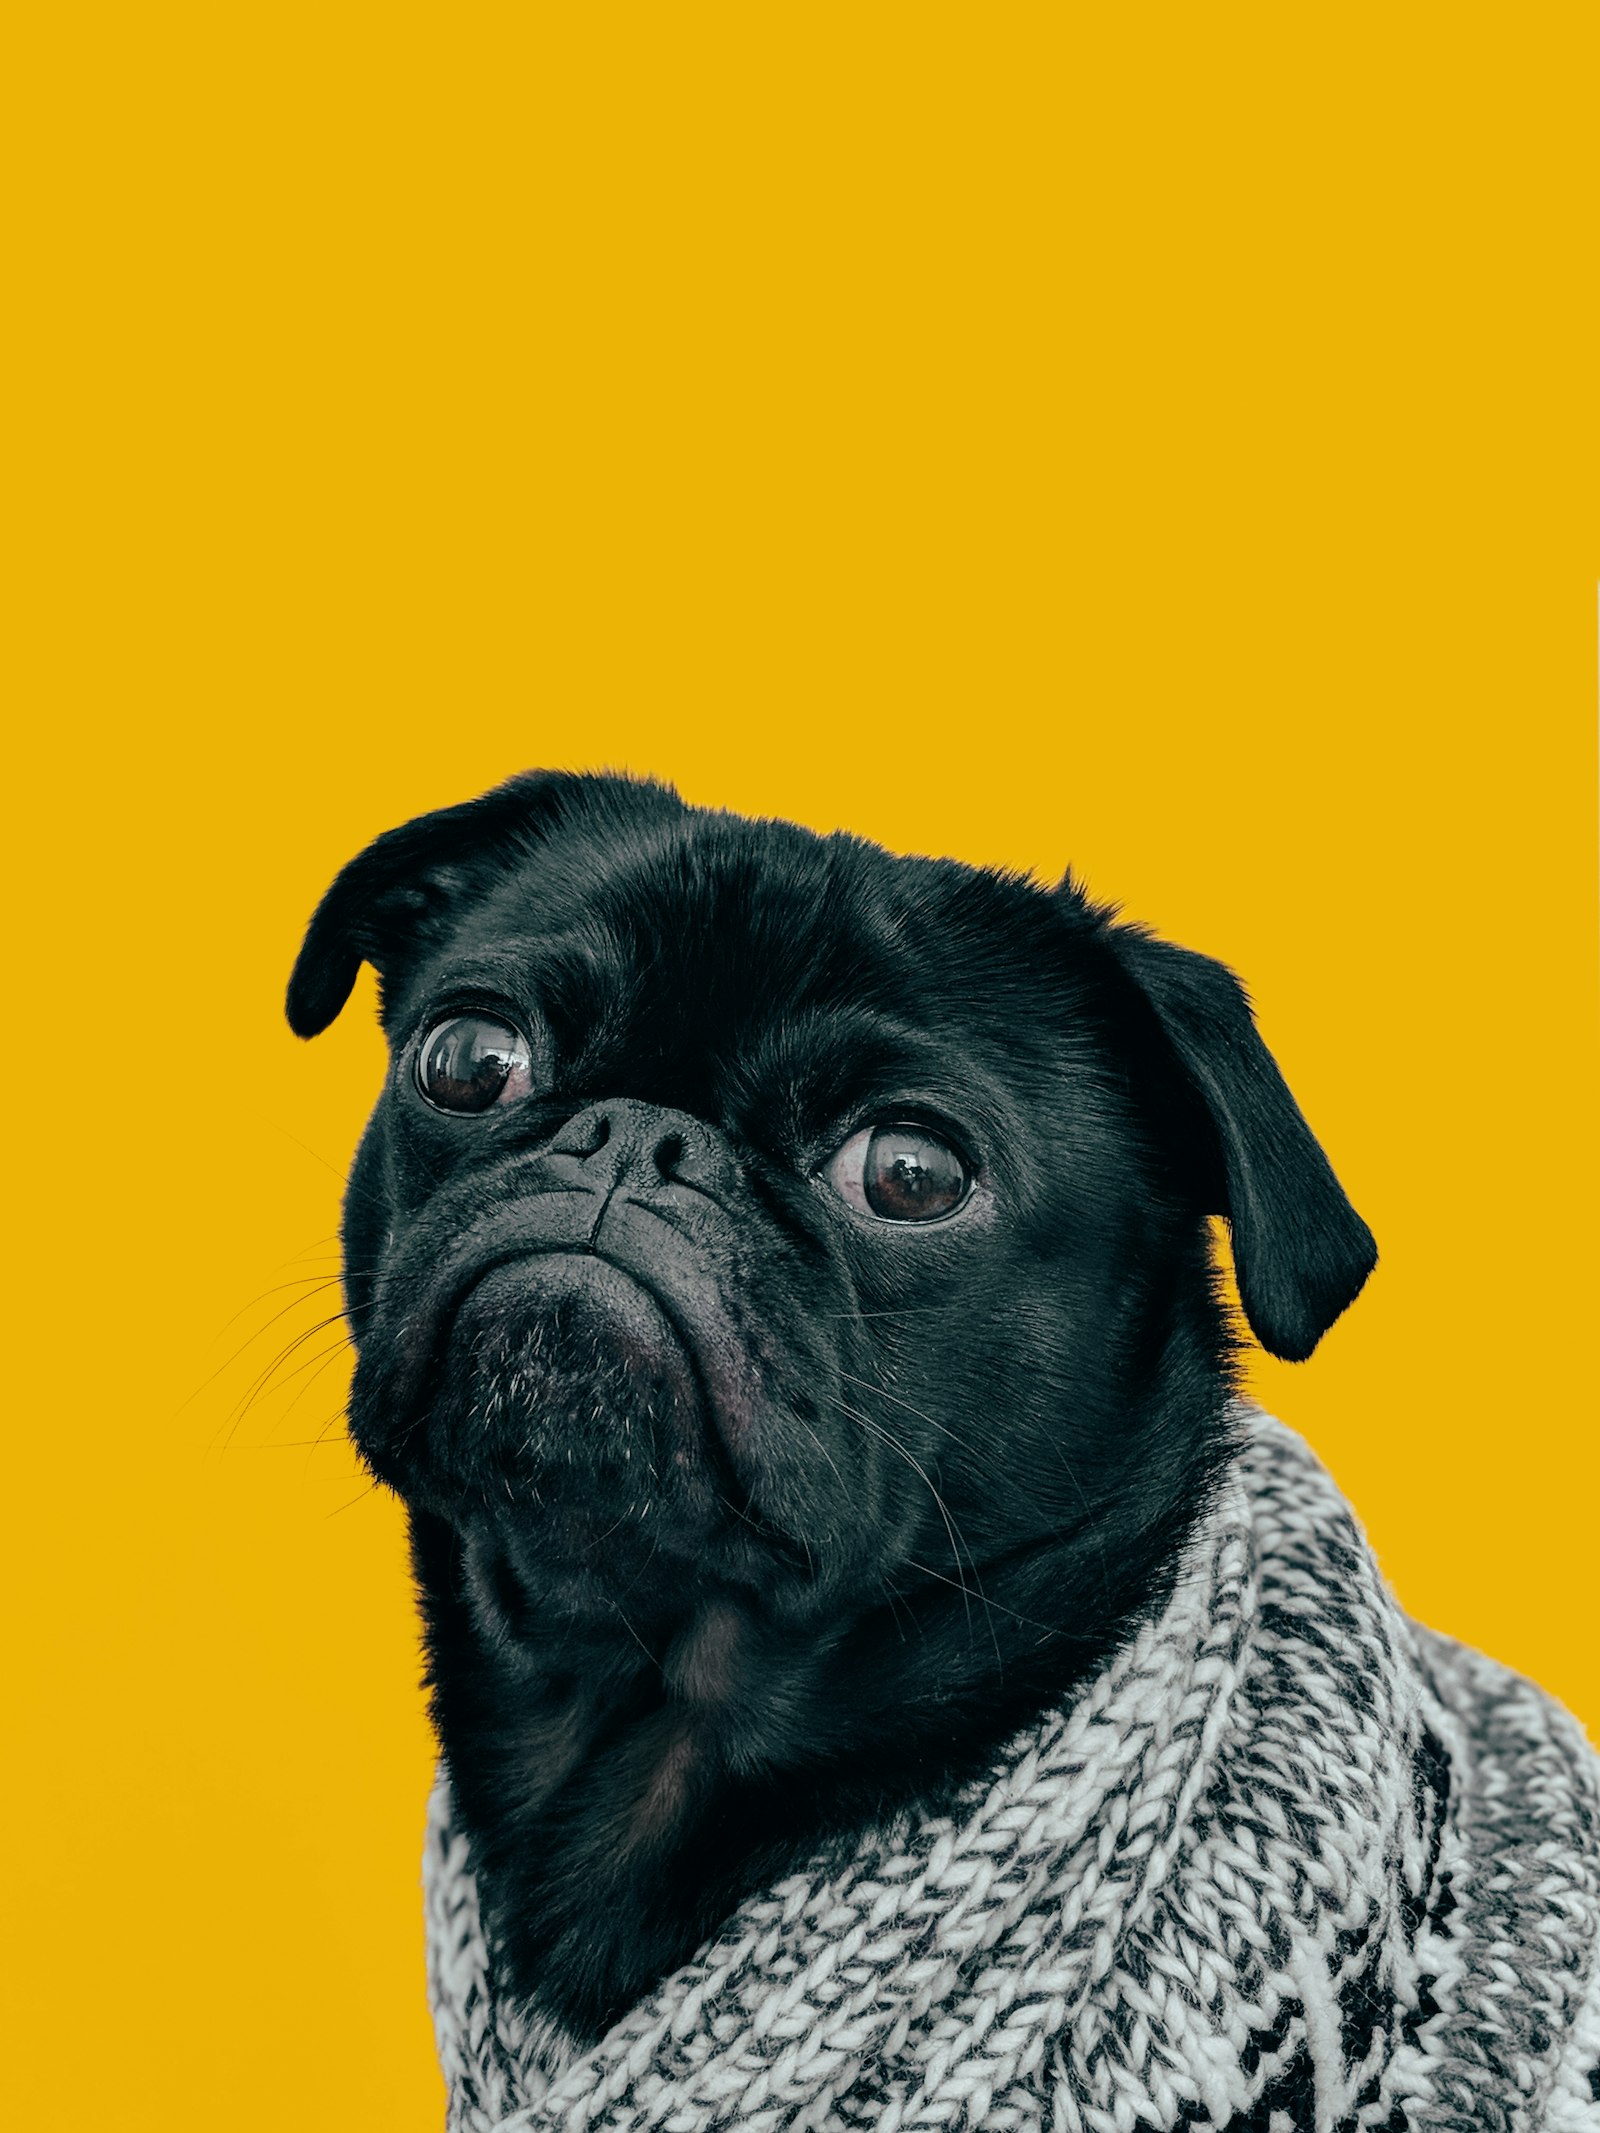
If a mixed-breed dog has brachycephalic features associated with pugs, boxers, French bulldogs, or English bulldogs, disclose them when applying for insurance. The insurer may classify the dog based on ancestral breeds, body structure, or a veterinary assessment, and may set exclusions for respiratory issues, anesthesia, or pre-existing symptoms.
The key is not to ask whether the dog “counts” as brachycephalic, but to confirm:
- Whether there are additional underwriting conditions or premium differences
- Whether coverage related to the airway, spine, and anesthesia is restricted
- How existing records of snoring, gagging, and poor exercise tolerance will be treated
- Whether a specific veterinary assessment or documentation is required before surgery
In terms of everyday care, brachycephalic dogs dissipate heat more slowly and should be kept out of the strongest sunlight. Water and shade should always be available. If your dog develops difficulty breathing, abnormally pale or bluish gums, fainting, or signs of heatstroke, seek emergency veterinary care immediately rather than waiting for confirmation that the claim is covered.
Q2: What documents are needed to file a claim?
Common documents include:
- The policy number and claim application form
- Receipts and itemized statements issued by the veterinary hospital
- Medical records, diagnosis certificates, and discharge summaries
- Test reports, imaging interpretations, pathology results, and laboratory results
- Prescriptions, medication names, and instructions for use
- Surgical records, anesthesia records, and hospitalization records
- A description or supporting evidence of an accidental injury
- The policyholder’s identification and bank account details
Different claims have different requirements. Before submitting a claim, confirm whether electronic or paper copies are accepted, whether original documents are required, and whether originals will be returned. If the original receipts must be mailed, photograph the complete itemized statement first and record the submission date.
Q3: Are there age restrictions?
Usually, yes. Different products may set a minimum enrollment age, and puppies may need to meet a minimum age or health requirement when applying. Older dogs may face higher premiums, coverage exclusions, or manual underwriting.
An older mixed-breed dog is not necessarily ineligible for coverage, but “can be insured now” should be distinguished from symptoms that developed during a previous waiting period. Increasing age at renewal may also affect rates and policy terms. Before applying, ask directly about the minimum and maximum ages, health requirements for puppies, and any age restrictions that apply after renewal.
The Paw Editor recommends keeping three sets of documents: the official policy terms, complete itemized billing statements, and written correspondence with customer support. First confirm that the coverage genuinely suits your mixed-breed dog’s age, medical history, and living environment, and then decide whether the premium offers good value.
Insurance product names, underwriting criteria, rates, and claims rules may change. The comparison method in this article does not replace the formal policy. Before applying for coverage, use the insurer’s latest policy terms and confirm the waiting periods, annual limits, deductibles, pre-existing-condition exclusions, and required claims documentation.